Your truck is stopped on the highway. The goods are going to a job worker, not a customer, so there is no invoice. The driver hands over a handwritten slip with no GSTIN, no HSN code and no value.
That slip can cost you 200% of the tax on the load.
This page gives you a free delivery challan format with 8 GST templates, an Excel sheet that tells you whether the load needs an e-way bill, and the rules most templates skip: which movements can travel on a challan at all, when a branch transfer needs a tax invoice instead, and the 1-3-6 Challan Clock that decides when a challan turns into a taxable supply. Marathi and Hindi versions are included.
Quick answer
A delivery challan format is a standard layout for the document that goes with goods when they move without a tax invoice, such as for job work, a same-GSTIN stock transfer or a sale on approval. Under Rule 55 of the CGST Rules it shows a challan number and date, consigner and consignee details with GSTIN, HSN code, quantity, taxable value and a signature.
- Rule 55 of the CGST Rules allows a delivery challan instead of a tax invoice only for job work, liquid gas of unknown quantity, movement not by way of supply, and other notified cases.
- Every challan needs a number of up to 16 characters, date, consigner and consignee GSTIN, HSN code, description, quantity, taxable value, place of supply for inter-State moves and a signature.
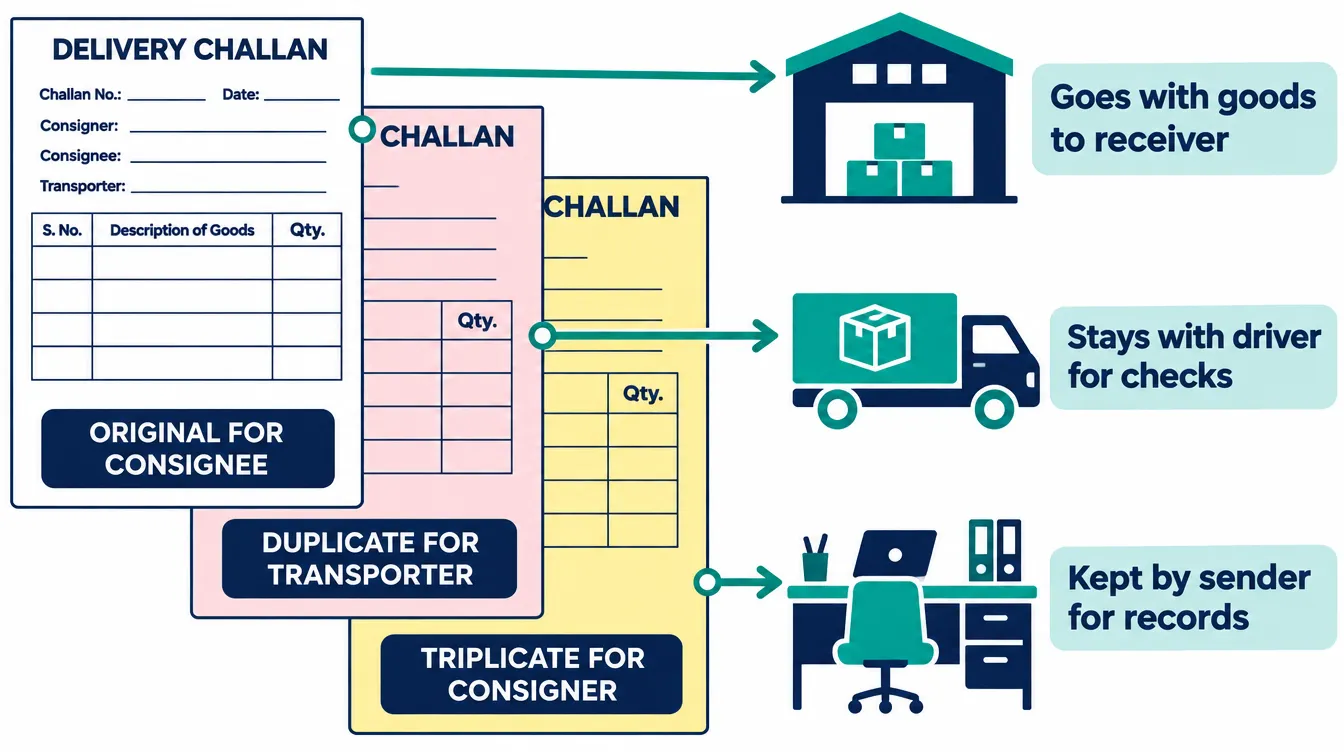
- A goods challan is made in three copies: Original for Consignee, Duplicate for Transporter and Triplicate for Consigner.
- Inter-State job work needs an e-way bill at any value; other moves need one above ₹50,000 inter-State, and above ₹1 lakh within Maharashtra.
- Job work inputs must return within 1 year and capital goods within 3 years, and goods sent on approval must be invoiced within 6 months of removal.
Contents
- Free delivery challan format: download
- What is a delivery challan?
- Delivery challan or tax invoice: which one do you need?
- What to include in a delivery challan format
- Does a delivery challan need an e-way bill?
- The 1-3-6 Challan Clock
- Job work challans and Form ITC-04
- How to make a delivery challan format in Excel
- 8 delivery challan format samples
- Common mistakes and the Section 129 penalty
- FAQ
Free delivery challan format: download
Download the delivery challan Excel file below. It totals the consignment value and flags when an e-way bill is required. Pick the template that matches why the goods are moving, add your letterhead, and print three copies.
Download delivery-challan-format.xlsx
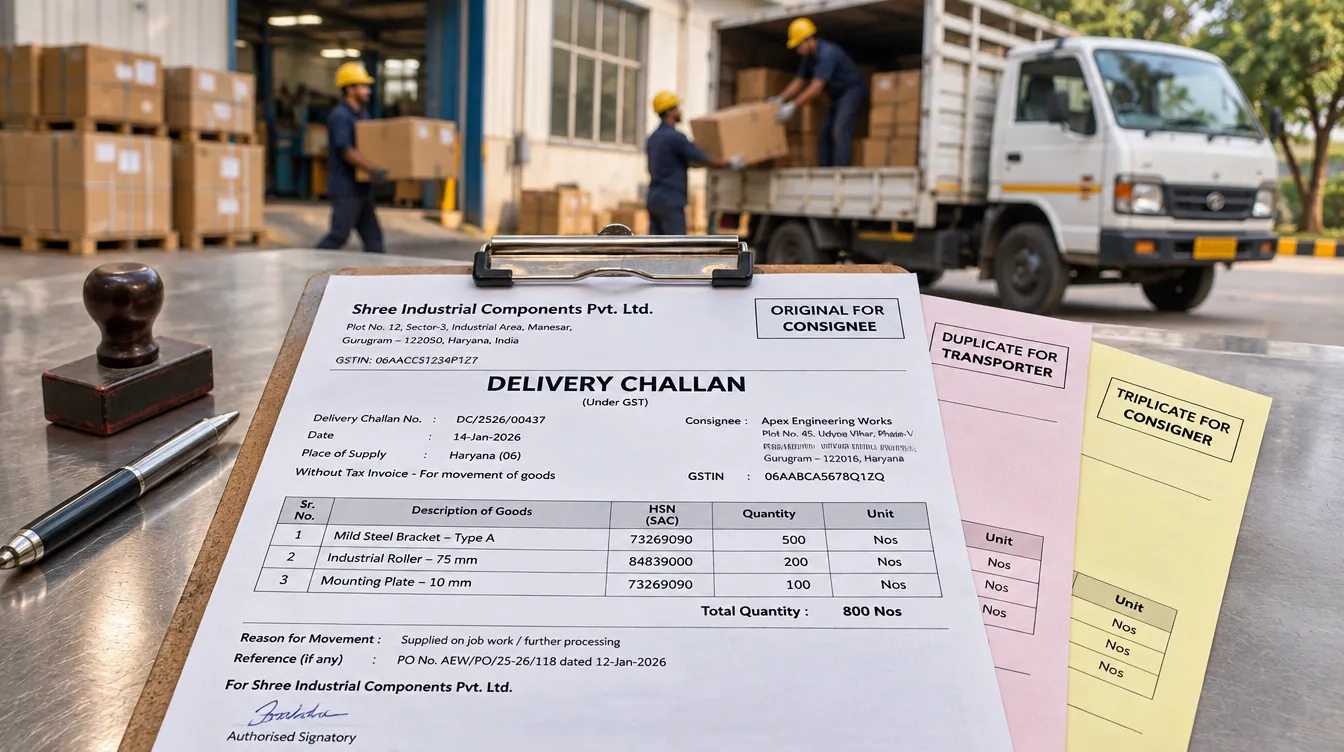
What is inside the pack:
| # | Template | Best for |
|---|---|---|
| 1 | Standard GST delivery challan (invoice to follow, lots, SKD/CKD) | Supplies where the invoice can’t go with the goods |
| 2 | Simple delivery challan format | Internal moves and small businesses that need a basic record |
| 3 | Job work delivery challan (principal to job worker) | Factories sending material for machining, plating, stitching |
| 4 | Job work return challan (job worker to principal) | Job workers sending processed goods back |
| 5 | Stock transfer challan (same GSTIN) | Warehouse to store or plant to godown in one state |
| 6 | Non-supply challan: approval, exhibition, sample, repair | Goods that may come back |
| 7 | Delivery challan format in Marathi (डिलिव्हरी चलन) | Job workers and transporters in Maharashtra |
| 8 | Delivery challan format in Hindi (डीलीवरी चालान) | Hindi-speaking parties across India |
The Excel file has the calculation and e-way bill check. The sample layouts for all 8 templates are copy-paste ready in the samples section below; and each one is also available as a free Word file under its heading.
What is a delivery challan?
A delivery challan is a document that goes with goods when they move without a tax invoice, either because no sale is happening yet or because the invoice can’t be issued at the time of removal. It proves what left your premises, where it is going and why, and it is the document the e-way bill is generated against.
Rule 55(1) of the CGST Rules lets the consigner issue a serially numbered challan of up to 16 characters, instead of an invoice, in four cases, as the rule text published by CGGST sets out:
- Liquid gas where the quantity is not known when it leaves the supplier.
- Job work, when you send goods to a job worker for processing.
- Movement for reasons other than supply, such as a same-GSTIN stock transfer, goods for exhibition, repair or approval.
- Other supplies notified by the Board.
Two more cases use a challan alongside an invoice. If the invoice could not be issued at removal, Rule 55(4) says it must be issued after delivery. And under Rule 55(5), goods sent in semi knocked down (SKD) or completely knocked down (CKD) condition, or in batches or lots, travel with a challan per lot that refers to one full invoice, with the original invoice going with the last lot.
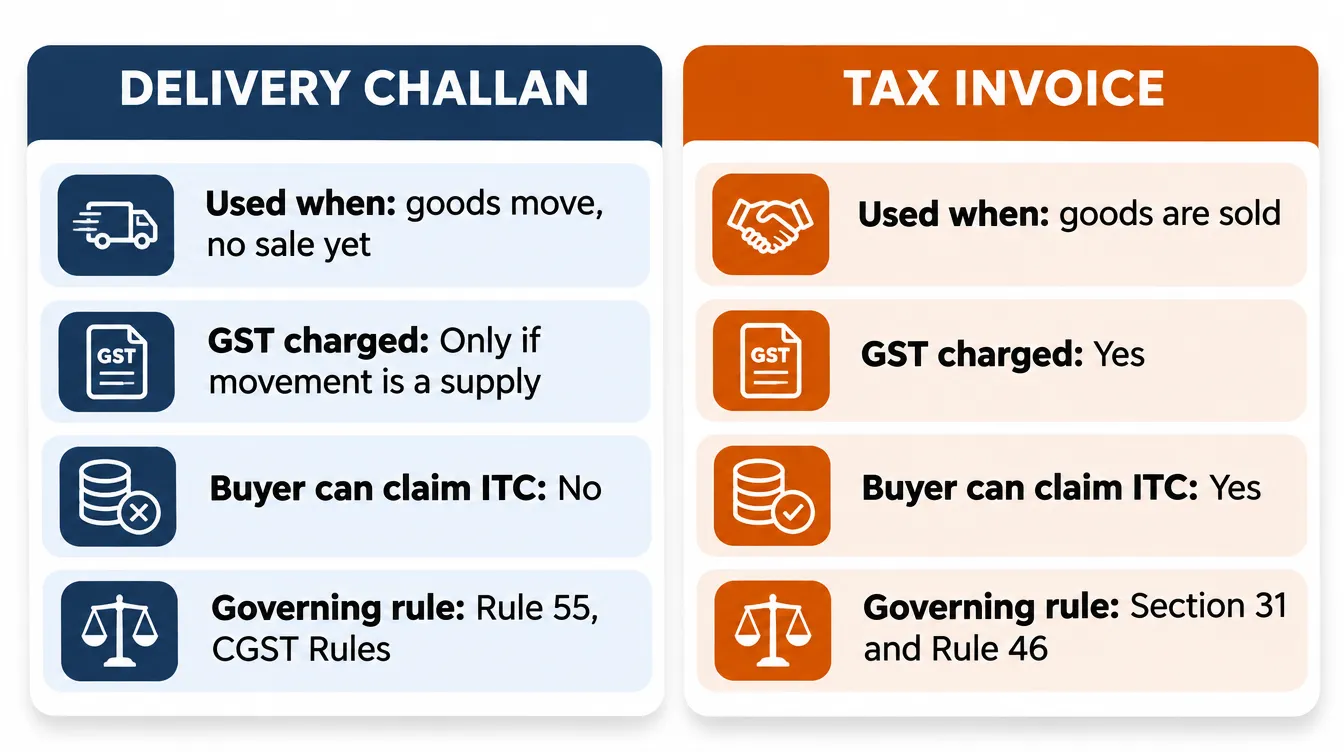
| Point | Delivery challan | Tax invoice |
|---|---|---|
| When used | Goods move, no sale yet (or invoice to follow) | Goods are sold |
| Law | Rule 55, CGST Rules | Section 31 CGST Act, Rule 46 |
| GST shown | Only where the movement is for supply to the consignee | Always, for taxable goods |
| Buyer’s input tax credit | Not available on a challan | Claimed on the invoice |
| E-invoice (IRN) | Not applicable | Applicable above the turnover limit |
| Reported in | GSTR-1 Table 13 (documents issued), ITC-04 for job work | GSTR-1 outward supplies |
Busy’s 2026 stock transfer checklist confirms e-invoicing does not apply to the challan itself (Busy), and challan details go in Table 13 of GSTR-1 (TaxGuru).
If the goods are being sold and you need the document that comes before the challan, see our purchase order format and quotation format in Word.
Delivery challan or tax invoice: which one do you need?
Use a delivery challan only when the movement is not a sale to another GSTIN; if it is a sale, including a transfer to your own branch with a different GSTIN, issue a tax invoice. This one decision causes more detentions than any missing field.
Ask two questions before the vehicle leaves: is it a supply, and is it to another GSTIN? Here is the table for the 12 movements Indian manufacturers and retail chains make most often:
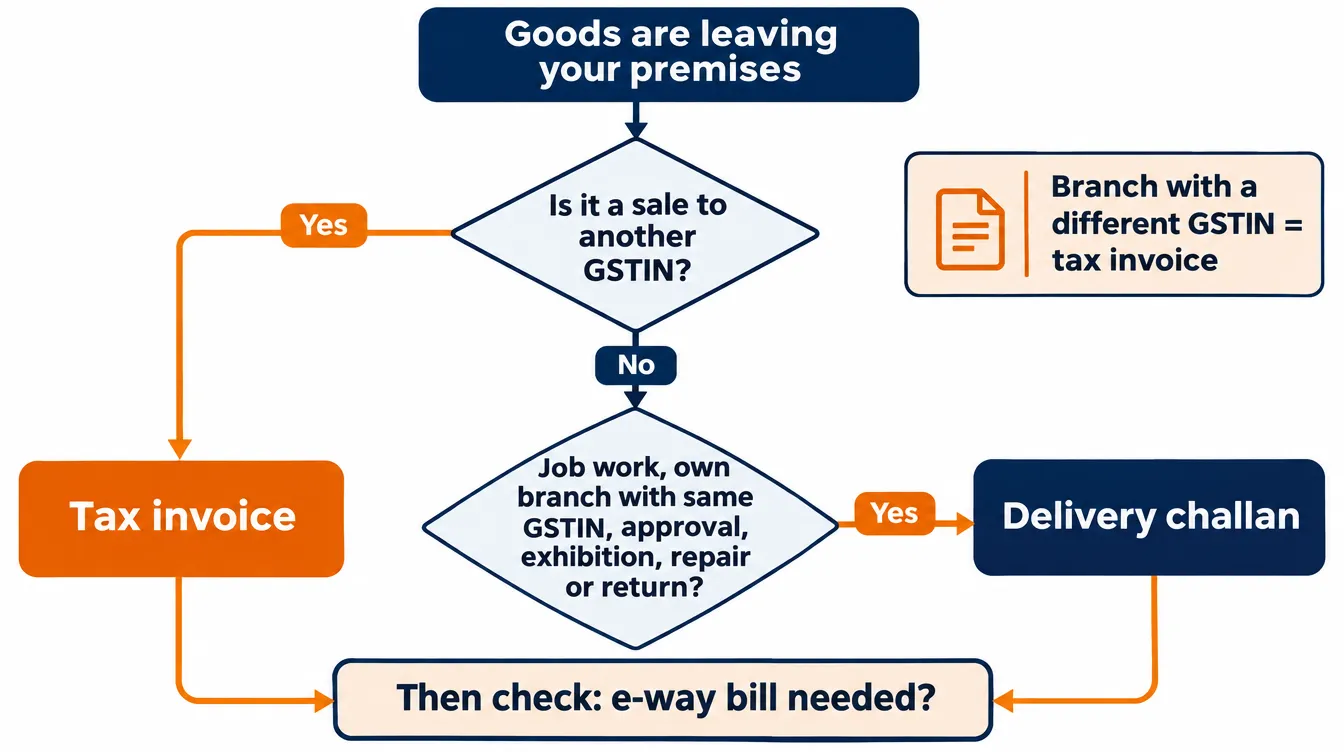
| # | Movement | Document | Why |
|---|---|---|---|
| 1 | Sale to a customer, invoice ready | Tax invoice | Supply; Section 31(1) |
| 2 | Sale, invoice can’t be issued at removal | Delivery challan, then invoice after delivery | Rule 55(4) |
| 3 | Large machine sent in SKD/CKD parts or lots | Full invoice before first lot + challan per lot | Rule 55(5) |
| 4 | Material to a job worker | Delivery challan | Rule 55(1)(b), Rule 45 |
| 5 | Processed goods back from job worker | Delivery challan (job worker’s or principal’s copy) | Circular 38/12/2018 |
| 6 | Warehouse to store, same GSTIN | Delivery challan | Not a supply |
| 7 | Branch in another state (different GSTIN) | Tax invoice | Distinct persons; supply even without payment |
| 8 | Goods sent on approval or sale-or-return | Delivery challan, invoice within 6 months | Section 31(7) |
| 9 | Goods to an exhibition or trade fair | Delivery challan | Not a supply |
| 10 | Machine or part sent for repair | Delivery challan | Not a supply |
| 11 | Free samples or demo units that come back | Delivery challan | Not a supply |
| 12 | Liquid gas, quantity unknown at removal | Delivery challan | Rule 55(1)(a) |
Same GSTIN or different GSTIN?
A stock transfer between two locations under the same GSTIN moves on a delivery challan, while a transfer to a location with a different GSTIN is a taxable supply that needs a tax invoice. Busy’s 2026 checklist puts it plainly: one GSTIN means a challan, and different GSTINs mean an invoice (Busy).
This matters for multi-outlet retail chains. A Pune warehouse sending stock to a Baramati store under the same Maharashtra GSTIN uses a challan. The same warehouse sending stock to its Bengaluru store, registered in Karnataka, must raise an IGST invoice.
Calling it a “branch transfer” in your books does not change that.
Sale on approval: the 6-month limit
Goods sent on approval travel on a delivery challan, but the tax invoice must be issued at the time of supply or within 6 months of removal, whichever is earlier, under Section 31(7) of the CGST Act (TaxManagementIndia). If the customer keeps the goods past 6 months without saying yes or no, you owe the invoice and the GST anyway.
What to include in a delivery challan format
A GST delivery challan format must carry the 9 particulars listed in Rule 55(1), and a usable one adds 6 more fields that make the challan easy to match, track and close. The legal minimum comes first.
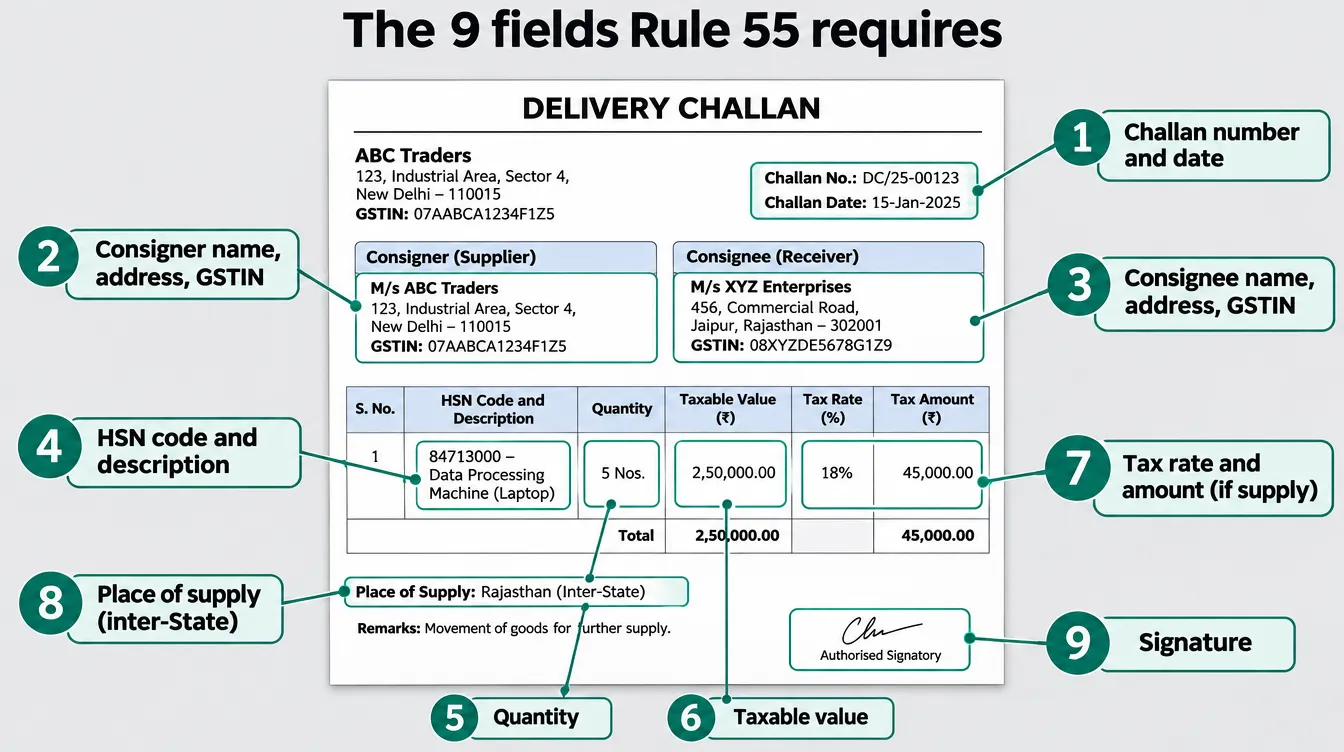
| # | Field (Rule 55(1)) | What to write |
|---|---|---|
| 1 | Date and number | Serial number of up to 16 characters, one series per financial year, e.g. DC/26-27/0041 |
| 2 | Consigner name, address, GSTIN | Your legal name and the GSTIN of the dispatching place |
| 3 | Consignee name, address, GSTIN or UIN | Receiver’s details; GSTIN if registered |
| 4 | HSN code and description | Same HSN you would put on an invoice |
| 5 | Quantity | Provisional quantity if exact quantity is unknown (liquid gas) |
| 6 | Taxable value | Value of goods, even when no tax is charged |
| 7 | Tax rate and amount | Only where the movement is for supply to the consignee (CGST + SGST or IGST) |
| 8 | Place of supply | For inter-State movement |
| 9 | Signature | Of the consigner or authorised person |
Six fields to add to every challan, because they prevent disputes and speed up checks:
| # | Extra field | Why it helps |
|---|---|---|
| 10 | Reason for movement | Job work, stock transfer, approval, repair; matches the e-way bill reason |
| 11 | Copy marking | Original for Consignee, Duplicate for Transporter, Triplicate for Consigner |
| 12 | Vehicle number and transporter | Matches Part B of the e-way bill |
| 13 | E-way bill number and date | Lets an officer link both documents fast |
| 14 | Expected return date | For job work, approval and repair challans |
| 15 | Receiver’s signature and date | Proof of delivery when the challan comes back |
Why three copies?
Rule 55(2) requires a goods delivery challan to be prepared in triplicate: the original marked “Original for Consignee”, the duplicate “Duplicate for Transporter” and the triplicate “Triplicate for Consigner”. That text is in the rule as reproduced by TaxManagementIndia and explained by TaxTMI.
For job work, the CBIC adds a practical step: the principal may send two copies to the job worker, and the job worker returns one with the processed goods, as TaxGuru’s summary of Circular 38/12/2018 notes. Keep that returned copy; it is your proof for ITC-04.
Does a delivery challan need an e-way bill?
A delivery challan needs an e-way bill when the consignment value crosses the threshold for that movement, and inter-State job work needs one at any value. Rule 55(3) says goods moved on a challan must be declared as specified in Rule 138, the e-way bill rule (CGGST).
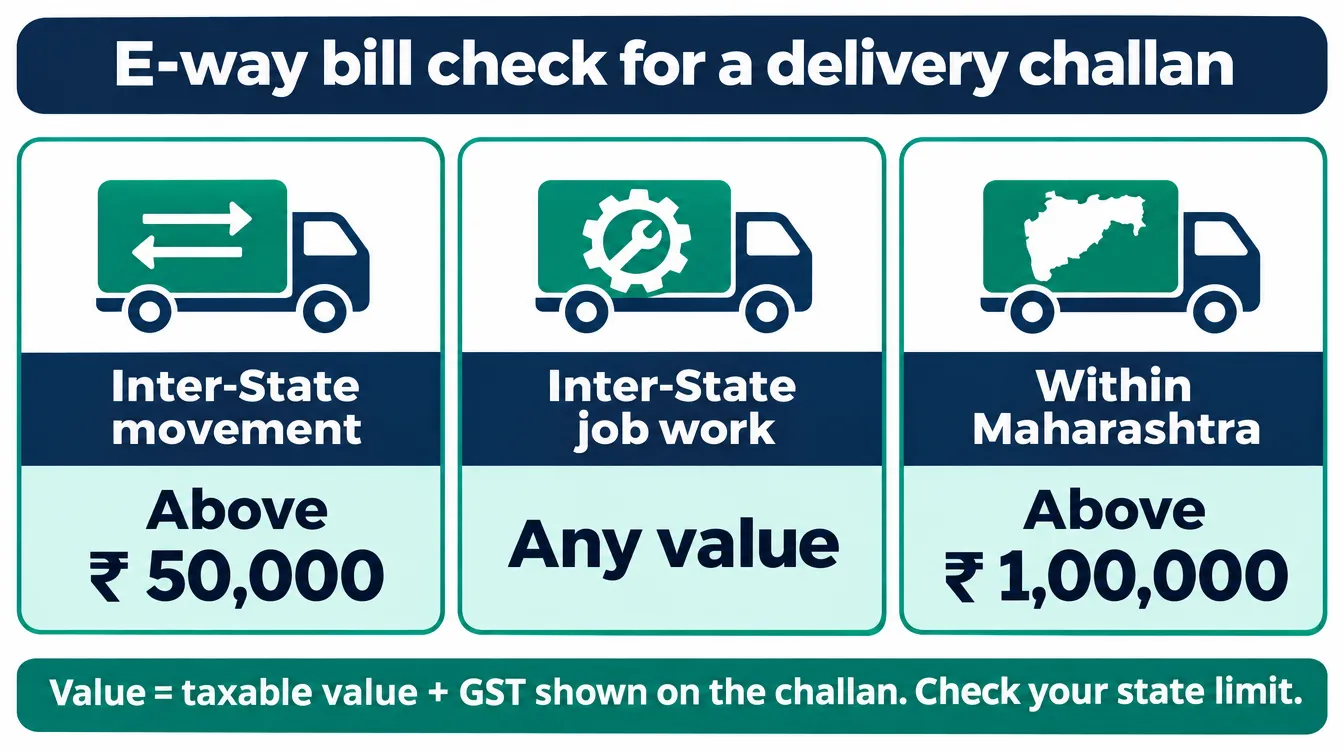
| Movement | E-way bill needed when | Source |
|---|---|---|
| Inter-State, any reason | Consignment value above ₹50,000 | Rule 138(1) |
| Inter-State job work (principal ↔ job worker) | Any value | Third proviso to Rule 138(1) |
| Within Maharashtra | Consignment value above ₹1,00,000 | Notification 15E/2018-State Tax |
| Within other states | As per that state’s notification (often ₹50,000) | State notifications |
Three things trip people up:
- The job work rule. The third proviso to Rule 138(1) says the principal or the registered job worker must generate the e-way bill for inter-State job work irrespective of consignment value (TaxGuru).
- The Maharashtra limit. No e-way bill is needed for movement that starts and ends within Maharashtra where the consignment value does not exceed ₹1 lakh, from 1 July 2018 (TaxGuru). Hank yarn, yarn, fabric and garments for job work within 50 km have extra relief under the same notification.
- Value includes tax. Consignment value under Explanation 2 to Rule 138 includes the tax shown on the document, as Petpooja’s template guide points out. On a job work challan with no tax, it is the taxable value.
Worked example. A Pune manufacturer sends aluminium castings worth ₹42,000 for machining.
| Job worker in | Movement | E-way bill? |
|---|---|---|
| Chakan, Maharashtra | Intra-State job work, ₹42,000 | No (below ₹1 lakh) |
| Vapi, Gujarat | Inter-State job work, ₹42,000 | Yes, at any value |
| Chakan, but value ₹1,20,000 | Intra-State, above ₹1 lakh | Yes |
When you generate it on the portal, choose Delivery Challan as the document type and pick the matching reason (Job Work, SKD/CKD, Exhibition or Fairs, For Own Use and so on), as Busy’s challan vs invoice guide explains. The same guide reports two e-way bill system changes scheduled from 1 August 2026: a mandatory Ship-to GSTIN in bill-to/ship-to cases and voluntary closure after delivery. Check the latest GSTN advisory before you rely on these dates.
Below the threshold? Rule 55A asks the driver to carry the tax invoice or bill of supply when no e-way bill is needed (CGGST). It does not replace the challan for non-supply movements. Send the printed challan with every load.
The 1-3-6 Challan Clock
The 1-3-6 Challan Clock is a simple way to track every open delivery challan: job work inputs must come back within 1 year, job work capital goods within 3 years, and goods sent on approval must be invoiced or returned within 6 months. Each clock starts on the challan date, and missing it turns the movement into a taxable supply.
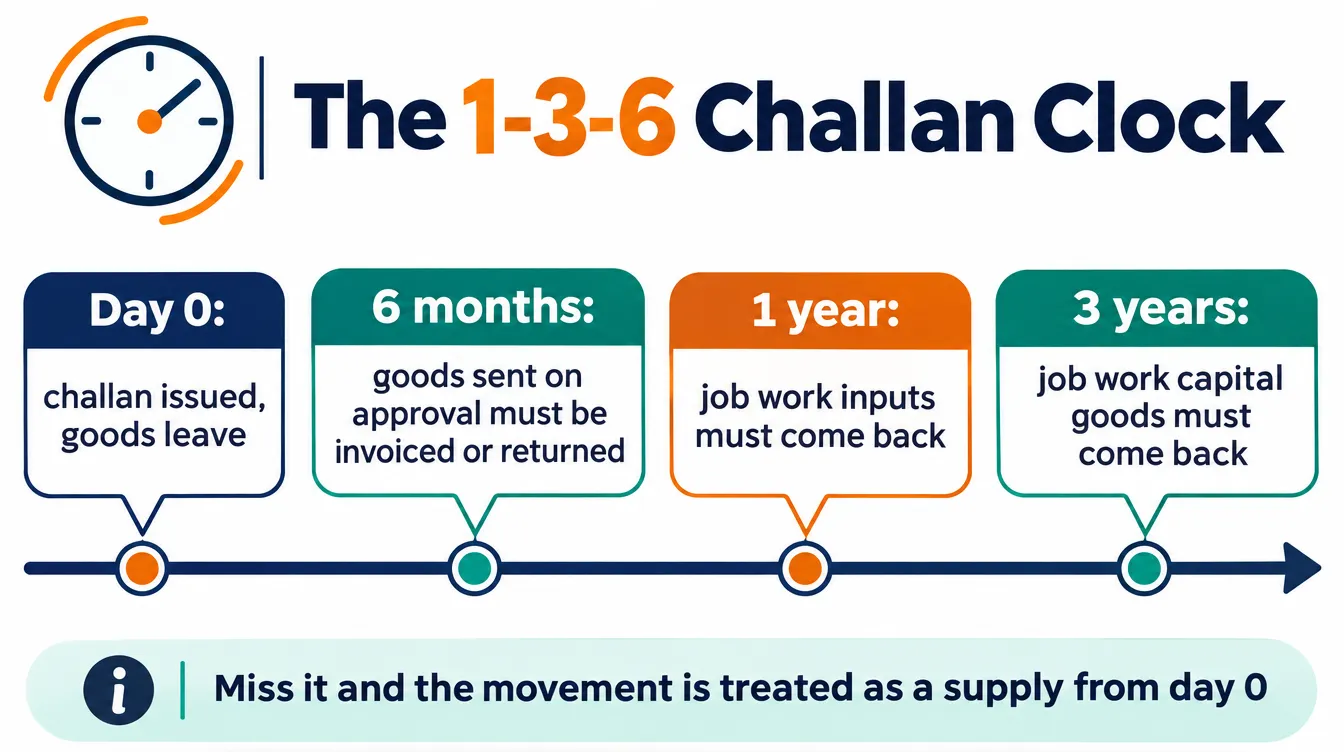
| Clock | Applies to | Law | If you miss it |
|---|---|---|---|
| 6 months | Goods sent on approval, sale or return | Section 31(7), CGST Act | Invoice and GST due at 6 months from removal |
| 1 year | Inputs sent for job work | Section 143(1)(a), CGST Act | Treated as supplied by you on the day they were sent |
| 3 years | Capital goods sent for job work | Section 143(1)(b), CGST Act | Same: deemed supply from the dispatch date |
Moulds, dies, jigs, fixtures and tools sent to a job worker are outside the 3-year limit, and the Commissioner can extend the 1-year and 3-year periods on sufficient cause, as Petpooja and GSTGyaan’s Section 143 guide summarise.
The deemed supply rule is what makes this expensive. If inputs don’t return in a year, you owe GST as if you sold them on the original dispatch date, with interest from then, according to Patron Accounting.
How to run the clock: add an “Expected return date” column to your challan register, calculate it with =EDATE(challan date, 12) for inputs, 36 for capital goods and 6 for approval, and review overdue challans every month. The Excel file in this pack does this for you.
Job work delivery challan format and Form ITC-04
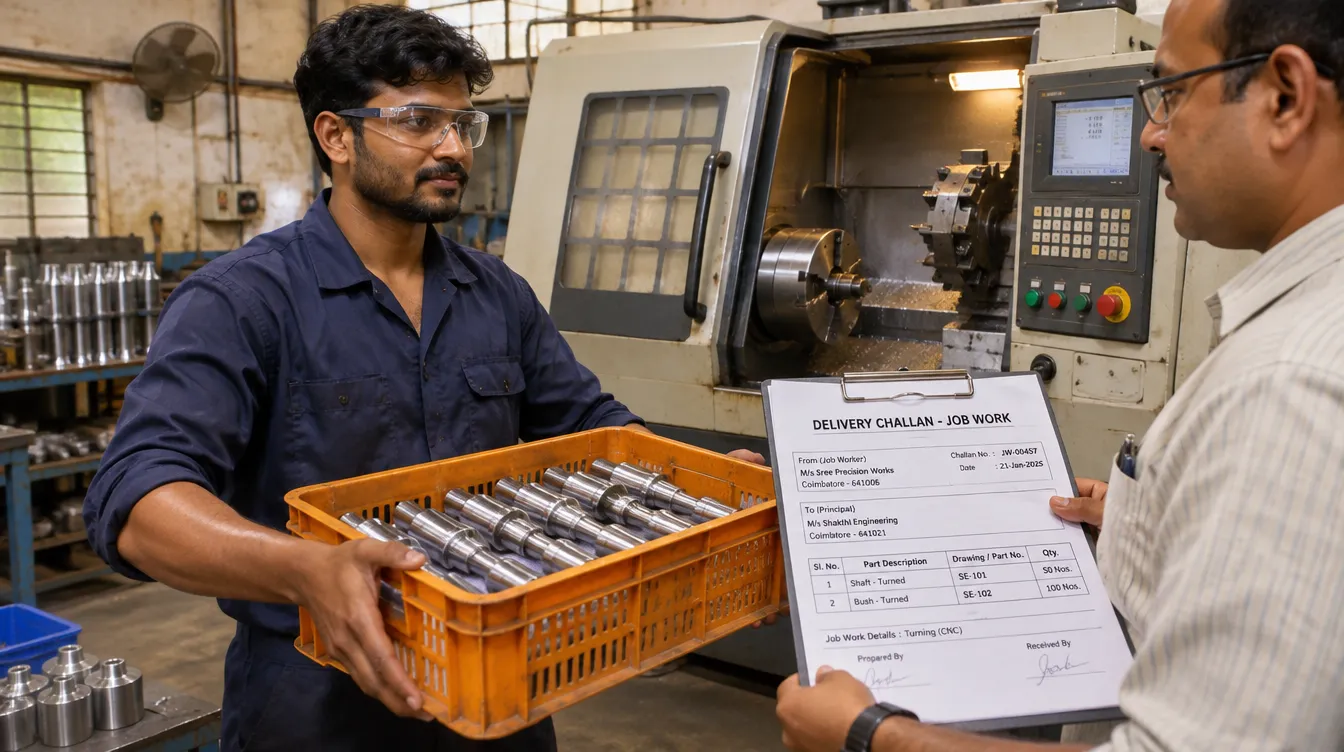
A job work delivery challan is issued by the principal under Rule 45 and Rule 55 for every movement of inputs, semi-finished goods or capital goods to a job worker, including goods sent straight from your supplier or from one job worker to another. That is the position of CBIC Circular 38/12/2018.
Three rules for a clean job work challan:
- Show taxable value, not tax. Rule 55(1) asks for tax only where the movement is for supply to the consignee. Sending goods for job work is not a supply, so declare the value of the goods and leave tax at nil.
- One challan per movement. Partial returns get their own return challan that quotes the original challan number.
- Report it in ITC-04. Every challan you issue to or receive back from a job worker goes into Form GST ITC-04.
Form ITC-04 frequency depends on the previous year’s aggregate turnover: above ₹5 crore it is half-yearly, due 25 October (April to September) and 25 April (October to March); up to ₹5 crore it is annual, due 25 April (TaxGuru). Oxyzo’s FY 2026-27 guide confirms the form, thresholds and due dates are unchanged this year (Oxyzo).
If you number your challans with a JW prefix (for example JW/26-27/0012), filtering them for ITC-04 takes minutes instead of a day.
How to make a delivery challan format in Excel with an e-way bill check
A delivery challan format in Microsoft Excel can total the consignment value, decide whether the movement is inter-State from the two GSTINs, flag when an e-way bill is required and calculate the return due date. It takes about 15 minutes to set up once.
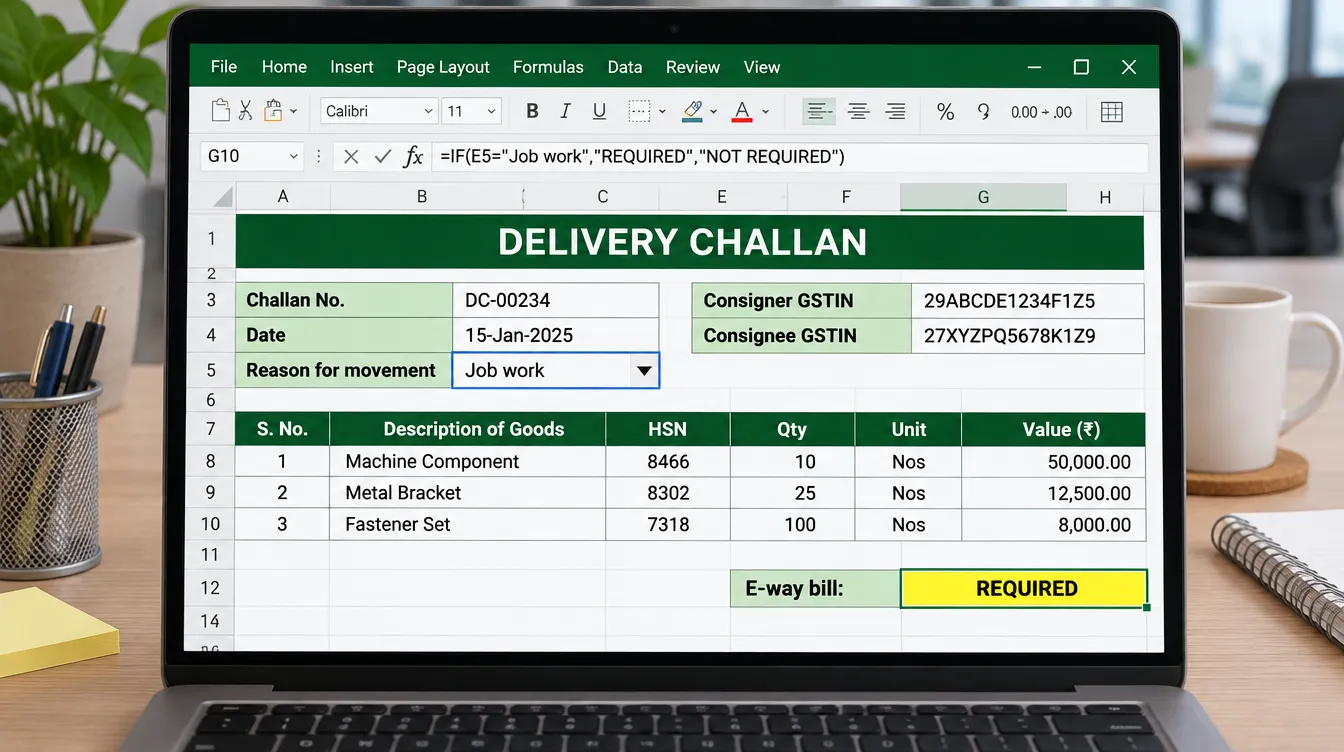
- Header. Rows 1 to 4: company name, address, GSTIN in C5. Put “DELIVERY CHALLAN” in bold, challan number in G2, challan date in G3, and your state’s intra-State e-way bill limit in G4 (100000 for Maharashtra).
- Reason dropdown. In C7, Data > Data Validation > List: Job work,Supply - invoice to follow,Stock transfer (same GSTIN),Sale on approval,Exhibition or sample,Repair or return,SKD/CKD lot.
- Consignee block. Consignee GSTIN in C9. Leave it blank for an unregistered consignee and type the state code in D9 instead.
- Item table from row 12. Columns: A Sr, B Description, C HSN, D Qty, E Unit, F Rate, G Value, H GST %, I Tax. In G12: =D12*F12. In I12: =IF($C$7="Supply - invoice to follow",G12*H12/100,0) so tax only appears for a supply. Copy down to row 21.
- Consignment value. In G23: =ROUND(SUM(G12:G21)+SUM(I12:I21),0).
- Inter-State or intra-State. In G24: =IF(LEFT(C5,2)=IF(C9="",D9,LEFT(C9,2)),"Intra-State","Inter-State"). The first two digits of a GSTIN are the state code (27 is Maharashtra, 24 is Gujarat).
- E-way bill flag. In G25: =IF(AND(C7="Job work",G24="Inter-State"),"REQUIRED",IF(G24="Inter-State",IF(G23>50000,"REQUIRED","Not required"),IF(G23>G4,"REQUIRED","Not required"))). Add conditional formatting to turn “REQUIRED” red.
- Return due date. In G26: =IF(C7="Job work",EDATE(G3,12),IF(C7="Sale on approval",EDATE(G3,6),"")). Change 12 to 36 for capital goods. Days left in G27: =IF(G26="","",G26-TODAY()).
Then set the print area, add “ORIGINAL FOR CONSIGNEE” in a header cell, and print three times with the label changed, or keep three identical sheets with the three markings. Save as an Excel template (.xltx).
One caution: the e-way bill flag is a check, not legal advice. State limits differ and some states exempt specific goods, so confirm your state’s notification.
Prefer Word? A delivery challan format in Microsoft Word works well for low-volume moves. Build the item table, then use Table Layout > Formula with =SUM(ABOVE) for the value total, and press F9 to refresh, as Microsoft’s guide to formulas in Word tables explains. Save as PDF to share a challan on WhatsApp or email.
8 delivery challan format samples (copy-paste ready)
Each delivery challan format sample below can be pasted into Word or Excel: replace the [bracketed] fields, add your letterhead, and print in triplicate.
1. Standard GST delivery challan format
When to use: Supplies where the tax invoice can’t go with the goods, goods sent in lots, or SKD/CKD consignments.
[Consigner Company Legal Name]
[Address, City, State, PIN] · GSTIN: [27XXXXX0000X1Z5] · Phone: [ ]
DELIVERY CHALLAN · [ORIGINAL FOR CONSIGNEE / DUPLICATE FOR TRANSPORTER / TRIPLICATE FOR CONSIGNER]
Challan No.: [DC/26-27/0001] · Date: [DD/MM/YYYY] · Reason: [Supply, invoice to follow / Lot [2] of [5] against Invoice No. [ ]]
Consignee: [Name, Address] · GSTIN: [ ] · Place of supply: [State]
Vehicle No.: [MH-42-XX-0000] · Transporter: [ ] · E-way bill No.: [ ]
| Sr | Description | HSN | Qty | Unit | Rate (₹) | Taxable value (₹) | GST % | Tax (₹) |
|---|---|---|---|---|---|---|---|---|
| 1 | [Item, size, grade] | [0000] | [ ] | [Nos] | [ ] | [ ] | 18 | [ ] |
| 2 | [Item] | [0000] | [ ] | [Kg] | [ ] | [ ] | 18 | [ ] |
| Total | [ ] | [ ] |
Consignment value (incl. tax): ₹[ ] · In words: Rupees [ ] only.
Note: Tax invoice will be issued [after delivery / with the last lot] under Rule 55 of the CGST Rules.
For [Consigner Company Legal Name]
[Authorised signature]
Received in good condition: Signature __________ Name __________ Date __________
2. Simple delivery challan format
When to use: Small businesses and internal moves that need a basic, readable record. This simple delivery challan format still keeps the Rule 55 fields.
[Business Name] · [Address] · GSTIN: [ ]
DELIVERY CHALLAN
Challan No.: [ ] · Date: [ ] · Reason: [ ]
To: [Name, Address, GSTIN if any]
| Sr | Description | HSN | Qty | Value (₹) |
|---|---|---|---|---|
| 1 | [ ] | [ ] | [ ] | [ ] |
| 2 | [ ] | [ ] | [ ] | [ ] |
| Total value | [ ] |
Vehicle No.: [ ] · Goods not for sale. [Delete if supply.]
For [Business Name]
[Signature] · Received by: __________
3. Job work delivery challan format (principal to job worker)
When to use: Sending raw material, semi-finished goods or tools to a job worker.
[Principal Company Legal Name] · [Plant address, MIDC] · GSTIN: [ ]
DELIVERY CHALLAN FOR JOB WORK (Rule 45 and Rule 55, CGST Rules) · [ORIGINAL / DUPLICATE / TRIPLICATE]
Challan No.: [JW/26-27/0001] · Date: [ ] · Job work order No.: [ ]
Job worker: [Name, Address] · GSTIN: [ ] · Place of supply: [State]
Process: [Machining / plating / heat treatment / stitching] · Expected return by: [date]
| Sr | Description | HSN | Qty sent | Unit | Taxable value (₹) | Type |
|---|---|---|---|---|---|---|
| 1 | [Aluminium casting, part no. ] | [7616] | [400] | Kg | [42,000] | Input |
| 2 | [Fixture no. ] | [8207] | [1] | Nos | [ ] | Tool (no time limit) |
| Total: [ ] |
Tax: Nil. Goods sent for job work under Section 143 of the CGST Act; not a supply.
Vehicle No.: [ ] · E-way bill No.: [Required for inter-State at any value]
Return of inputs within 1 year and capital goods within 3 years of this date.
For [Principal Company]
[Signature] · Received by job worker: __________ Date: __________
4. Job work return challan format (job worker to principal)
When to use: Job workers returning processed goods, scrap or rejects to the principal.
[Job Worker Name] · [Address] · GSTIN: [ ]
DELIVERY CHALLAN: RETURN AFTER JOB WORK
Challan No.: [ ] · Date: [ ] · Against principal’s challan No.: [JW/26-27/0001] dated [ ]
To: [Principal name, address, GSTIN]
| Sr | Description | HSN | Qty received | Qty returned | Process loss / scrap | Balance with us |
|---|---|---|---|---|---|---|
| 1 | [Machined casting] | [7616] | [400 kg] | [388 kg] | [12 kg] | [0] |
Job work charges billed separately on Invoice No. [ ].
For [Job Worker]
[Signature] · Received by principal: __________
5. Stock transfer delivery challan format (same GSTIN)
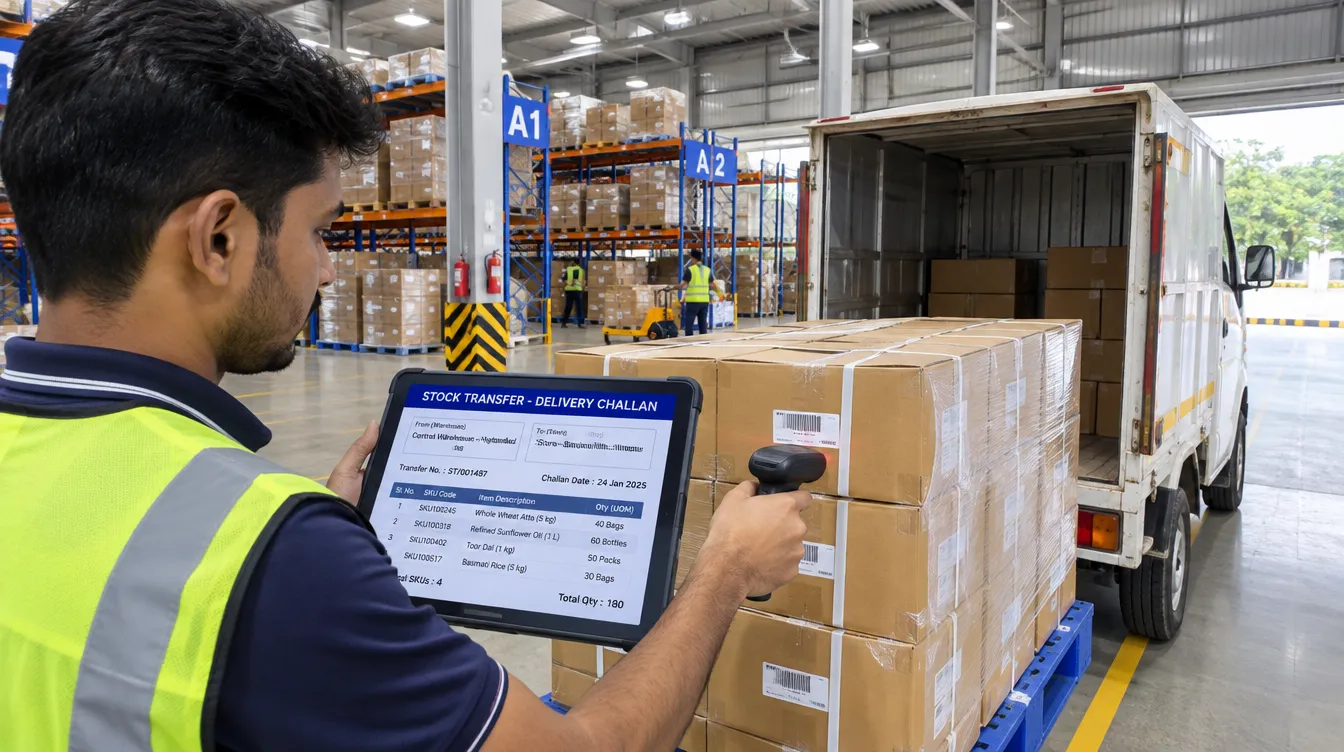
When to use: Warehouse to store, plant to godown, or store to store within the same state and the same GSTIN. For a different GSTIN, raise a tax invoice instead.
[Company Legal Name] · GSTIN: [27XXXXX0000X1Z5]
DELIVERY CHALLAN: STOCK TRANSFER (SAME GSTIN)
Challan No.: [ST/26-27/0001] · Date: [ ]
From: [Central warehouse, address] → To: [Store / godown, address] (same GSTIN)
| Sr | SKU / product | HSN | Qty | Unit | Value at cost (₹) |
|---|---|---|---|---|---|
| 1 | [ ] | [ ] | [ ] | [ ] | [ ] |
| 2 | [ ] | [ ] | [ ] | [ ] | [ ] |
| Total | [ ] |
Movement within the same registered person; not a supply. No tax charged.
Dispatched by: __________ · Received at store by: __________ Date: __________
6. Non-supply delivery challan: approval, exhibition, sample, repair
When to use: Goods that leave and may come back: sale on approval, trade fairs, demo units, machines sent for repair.
[Company Legal Name] · GSTIN: [ ]
DELIVERY CHALLAN: [SALE ON APPROVAL / EXHIBITION / DEMO / REPAIR]
Challan No.: [NS/26-27/0001] · Date: [ ] · Expected return / decision by: [date]
To: [Name, Address, GSTIN] · Place of supply: [State, if inter-State]
| Sr | Description | Serial / model no. | HSN | Qty | Taxable value (₹) |
|---|---|---|---|---|---|
| 1 | [ ] | [ ] | [ ] | [ ] | [ ] |
Goods sent [on approval; tax invoice will be issued on approval or within 6 months of removal, whichever is earlier (Section 31(7), CGST Act) / for exhibition and will be returned / for repair and return].
For [Company]
[Signature] · Received by: __________
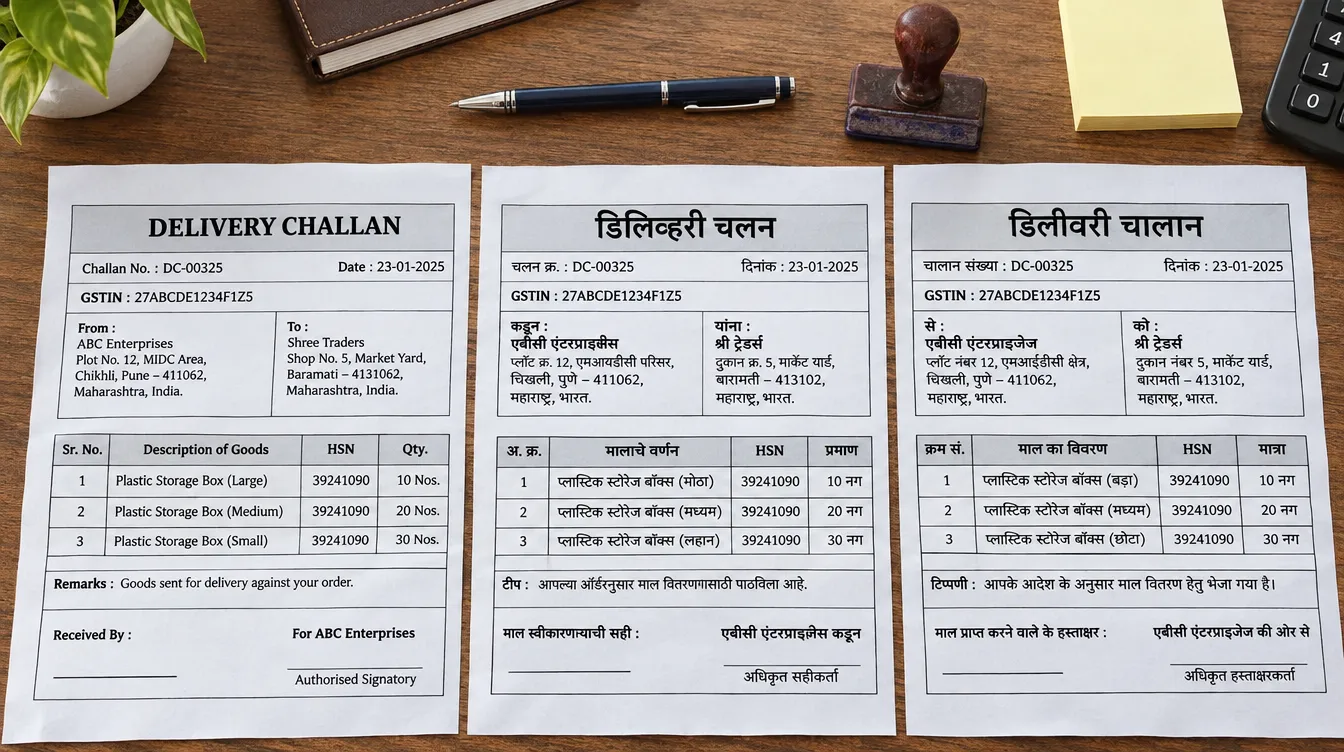
7. Delivery challan format in Marathi (डिलिव्हरी चलन)
When to use: Job workers, fabricators and transporters in Maharashtra who prefer Marathi. Keep GSTIN, HSN and numbers in English digits so they match the e-way bill.
[कंपनीचे नाव] · [पत्ता] · GSTIN: [ ]
डिलिव्हरी चलन (DELIVERY CHALLAN) · [ग्राहकासाठी मूळ प्रत / वाहतूकदारासाठी दुसरी प्रत / पाठवणाऱ्यासाठी तिसरी प्रत]
चलन क्र.: [ ] · दिनांक: [ ] · माल पाठवण्याचे कारण: [जॉब वर्क / स्टॉक ट्रान्सफर / दुरुस्ती]
प्रति: [नाव, पत्ता] · GSTIN: [ ]
| अ.क्र. | मालाचे वर्णन | HSN | नग / वजन | किंमत (₹) |
|---|---|---|---|---|
| 1 | [ ] | [ ] | [ ] | [ ] |
| 2 | [ ] | [ ] | [ ] | [ ] |
| एकूण किंमत | [ ] |
वाहन क्र.: [ ] · ई-वे बिल क्र.: [ ]
हा माल विक्रीसाठी नाही. [विक्री असल्यास ही ओळ काढा.] जॉब वर्कचा माल [दिनांक] पर्यंत परत करावा.
[कंपनीचे नाव] करिता
[सही व शिक्का] · माल मिळाल्याची सही: __________
8. Delivery challan format in Hindi (डीलीवरी चालान)
When to use: Hindi-speaking job workers, dealers and transporters.
[कंपनी का नाम] · [पता] · GSTIN: [ ]
डीलीवरी चालान (DELIVERY CHALLAN) · [प्राप्तकर्ता हेतु मूल प्रति / ट्रांसपोर्टर हेतु दूसरी प्रति / प्रेषक हेतु तीसरी प्रति]
चालान सं.: [ ] · दिनांक: [ ] · माल भेजने का कारण: [जॉब वर्क / स्टॉक ट्रांसफर / मरम्मत]
सेवा में: [नाम, पता] · GSTIN: [ ]
| क्र.सं. | विवरण | HSN | मात्रा | मूल्य (₹) |
|---|---|---|---|---|
| 1 | [ ] | [ ] | [ ] | [ ] |
| 2 | [ ] | [ ] | [ ] | [ ] |
| कुल मूल्य | [ ] |
वाहन सं.: [ ] · ई-वे बिल सं.: [ ]
यह माल बिक्री के लिए नहीं है। [बिक्री हो तो यह पंक्ति हटाएँ।]
[कंपनी का नाम] के लिए
[हस्ताक्षर और मुहर] · माल प्राप्ति हस्ताक्षर: __________
Common challan mistakes and the Section 129 penalty
Most challan problems come from using a challan where an invoice is needed, or sending goods with a challan that is missing a GSTIN, value or e-way bill. If an officer finds goods moving in breach of the rules, Section 129 of the CGST Act allows detention. As the ICMAI GST deck summarises, release generally needs a penalty of 200% of the tax payable when the owner comes forward, or 2% of value or ₹25,000 (whichever is less) for exempt goods. Confirm the current figures with your CA before you rely on them.
On a load with taxable value of ₹80,000 at 18% GST, the tax is ₹14,400, so a 200% penalty is ₹28,800, plus days of a stuck truck.
Courts have set aside some penalties for minor clerical slips with no intent to evade, but you don’t want to test that on every trip.
| Mistake | What happens | Fix |
|---|---|---|
| Challan used for a sale | Tax not paid on time; detention risk | Issue a tax invoice; challan only under Rule 55(4) |
| Challan for transfer to a branch with a different GSTIN | Supply without invoice; GST and ITC mismatch | Raise a tax invoice (IGST if inter-State) |
| No value on a job work challan | E-way bill can’t be checked; challan defective | Show taxable value; tax nil |
| No e-way bill for inter-State job work under ₹50,000 | Detention under Section 129 | Generate one at any value |
| One copy only | Driver has nothing for checks; no office record | Print in triplicate with markings |
| Handwritten, unnumbered challan | Can’t match to e-way bill, GSTR-1 or ITC-04 | Use a serial series up to 16 characters |
| Approval goods forgotten | Invoice and GST due at 6 months anyway | Track the 1-3-6 Challan Clock monthly |
| Job work inputs not back in a year | Deemed supply from dispatch date, with interest | Chase returns at month 10; ask for extension if needed |
A delivery challan in Word or Excel works well until you have dozens of open challans across job workers, stores and approval customers, and nobody can say which ones are overdue. For stock that moves between outlets and godowns, see our guide to inventory management software.
FAQ: delivery challan format
What is the format of a delivery challan?
A delivery challan format has the consigner’s name, address and GSTIN, a challan number of up to 16 characters and date, the consignee’s name, address and GSTIN, HSN code, description, quantity, taxable value, tax rate and amount where the movement is a supply, place of supply for inter-State moves and a signature, as Rule 55 of the CGST Rules requires.
When is a delivery challan issued under GST?
A delivery challan is issued instead of a tax invoice for job work, liquid gas of unknown quantity, movement not by way of supply (such as a same-GSTIN stock transfer, exhibition, repair or sale on approval) and other notified cases. It is also used with an invoice for goods sent in lots or SKD/CKD condition.
How many copies of a delivery challan are required?
Three copies are required for goods: the original marked Original for Consignee, the duplicate marked Duplicate for Transporter and the triplicate marked Triplicate for Consigner, under Rule 55(2) of the CGST Rules.
Is an e-way bill required with a delivery challan?
Yes, when the consignment value crosses the threshold: above ₹50,000 for inter-State moves and the state limit for intra-State moves (₹1 lakh in Maharashtra). Inter-State movement between a principal and a job worker needs an e-way bill at any value.
Can a delivery challan be used for stock transfer?
Yes, if both locations are under the same GSTIN, because the movement is not a supply. A transfer to your branch with a different GSTIN, such as another state, is a taxable supply and needs a tax invoice.
Is GST charged on a delivery challan?
GST is shown on a delivery challan only where the goods are moving for supply to the consignee, for example when the invoice follows after delivery. For job work, stock transfers within one GSTIN, exhibitions and repairs, the challan shows the taxable value with no tax.
How do I make a delivery challan format in Excel?
Build an item table with Qty, Rate and Value columns, total the consignment value with =ROUND(SUM(value)+SUM(tax),0), compare the first two digits of both GSTINs to decide inter-State or intra-State, and use an IF formula to flag “REQUIRED” for an e-way bill when the value crosses the limit or the movement is inter-State job work.
Can I download a delivery challan format for free?
Yes. The Excel file on this page is free and includes the e-way bill check. Each of the 8 sample layouts is also available as a free Word file.
Sources
- Rule 55, CGST Rules 2017: transportation of goods without issue of invoice, CGGST, 2025
- Rule 55, CGST Rules: triplicate copy markings, TaxManagementIndia
- Procedure for issuing a delivery challan, TaxTMI
- Rule 55A, CGST Rules: invoice to accompany goods where no e-way bill, CGGST, 2025
- Circular No. 38/12/2018-GST on job work, CBIC / GST Council, March 2018
- Job work under GST: challan copies and GSTR-1 Table 13, TaxGuru
- E-way bill for job work: third proviso to Rule 138(1), TaxGuru
- Maharashtra Notification 15E/2018-State Tax: ₹1 lakh intra-State limit, TaxGuru, June 2018
- E-way bill for delivery challan vs tax invoice, Busy, August 2026
- E-way bill checklist for stock transfers in 2026, Busy, August 2026
- Goods sent on approval: Section 31(7), TaxManagementIndia
- Section 143 job work procedure guide, GSTGyaan
- ITC-04 due dates for FY 2026-27, TaxGuru, October 2026
- GST ITC-04 filing FY 2026-27, Oxyzo, 2026
- Form ITC-04 job work tracking and deemed supply, Patron Accounting, 2026
- Section 129 penalties after 1 January 2022, ICMAI, 2024
- Delivery challan format in Excel for GST-registered businesses, Petpooja, September 2026
- Use a formula in a Word table, Microsoft Support
These templates are general information, not legal or tax advice. Confirm GST treatment, e-way bill limits for your state and job work timelines with your CA.